Blog
5 Proven Ways to Protect Your Assets: A Practical Guide to Financial Security

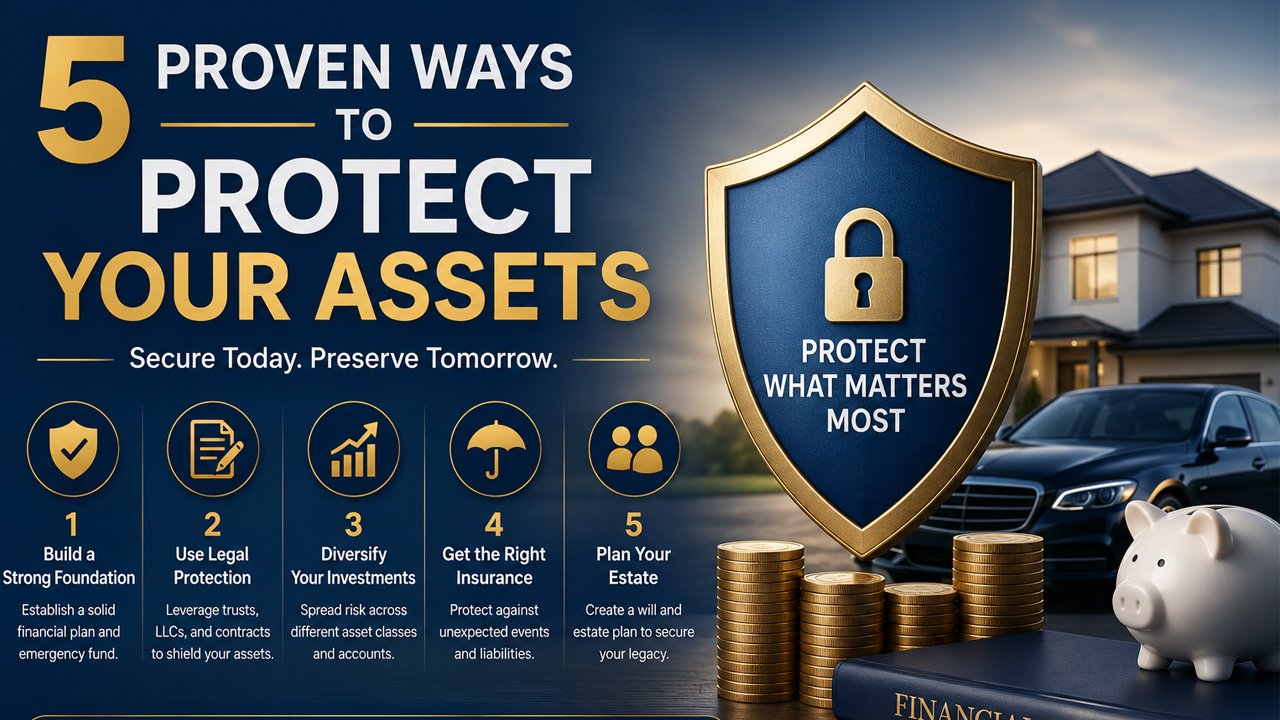
Asset protection refers to a genuine, well-established set of legal and financial strategies people use to reduce the risk of losing savings, property, or investments to lawsuits, creditors, or unexpected life events, and financial institutions including Fidelity, Western & Southern, and numerous estate planning attorneys have published consistent, overlapping guidance on which strategies actually work. This article covers five genuinely proven approaches, why each one matters, and how to think about building a reasonable protection plan suited to your own circumstances.
Why Does Asset Protection Matter in the First Place?
Asset protection matters because unexpected lawsuits, business liabilities, divorce proceedings, or creditor claims can put a lifetime of savings and property at genuine risk, even for people who haven’t done anything wrong, since accidents, disputes, and business downturns happen regardless of how careful someone tries to be. Business owners, landlords, medical professionals, and anyone holding significant personal assets face measurably higher exposure to this kind of risk than the general population, since their professional activities create more opportunities for disputes or claims to arise.
Planning proactively, before a specific threat exists, is considerably more effective and legally sound than trying to shield assets after a lawsuit has already been filed, since many jurisdictions have fraudulent transfer laws specifically designed to unwind asset transfers made to evade a known, pending claim.
1. Adequate Insurance Coverage
Sufficient insurance, homeowners or renters coverage, auto insurance with adequate liability limits, professional liability coverage for business owners, and specifically umbrella liability policies that extend coverage well beyond standard policy limits, represents the most fundamental and broadly recommended asset protection strategy across nearly every financial institution’s published guidance. An umbrella policy specifically is designed to activate once the liability limits on your underlying auto or homeowners policy are exhausted, providing an additional layer of protection that can be the difference between a manageable settlement and a judgment that reaches into personal savings or property.
Reviewing coverage limits periodically, rather than assuming a policy purchased years ago still provides adequate protection, is a genuinely important practice, since asset values, income, and personal liability exposure typically increase over time in ways that can outpace an unchanged, older insurance policy.
2. Business Entity Structuring
Operating a business through a properly formed and maintained legal entity, a limited liability company or corporation rather than as a sole proprietorship, is a well-documented strategy for creating legal separation between personal assets and business liabilities. This separation, often called the “corporate veil,” generally protects personal assets from business debts and lawsuits, provided the entity is genuinely maintained through proper formalities like separate bank accounts, adequate capitalization, and accurate recordkeeping, since courts can and do “pierce the corporate veil” when an entity is treated as a mere formality rather than a genuinely separate legal structure.
Consulting a qualified business attorney about the specific entity structure and formalities appropriate for a particular business and state is a reasonable step, since entity requirements and protections vary meaningfully across different jurisdictions. The Internal Revenue Service’s overview of business structures provides a useful, authoritative starting point for understanding how different entity types are treated for tax and liability purposes.
3. Retirement Account Protections
Many retirement accounts, including employer-sponsored 401(k) plans and, to varying degrees depending on state law, individual retirement accounts, receive strong legal protection from creditors under federal law, specifically the Employee Retirement Income Security Act for qualified employer plans, making them a genuinely reliable place to accumulate long-term savings with built-in creditor protection. This protection generally applies even in bankruptcy proceedings, reflecting a deliberate public policy choice to preserve retirement security even when other assets are exposed to creditor claims.
State-level protection for IRAs specifically varies considerably, so understanding your particular state’s specific rules, rather than assuming uniform nationwide protection, is a genuinely useful step for anyone relying heavily on IRA savings as part of a broader asset protection approach.
4. Trusts for Long-Term Planning
Certain types of trusts, particularly irrevocable trusts established well before any specific legal threat arises, can provide genuine, legally recognized asset protection by transferring legal ownership of assets out of an individual’s personal name while still allowing for structured, controlled benefit to intended beneficiaries. Domestic asset protection trusts, available in certain states with specific favorable trust legislation, and irrevocable life insurance trusts are among the more commonly used structures for this purpose, though trust law is genuinely complex and varies considerably by state and specific goals.
Because establishing an effective trust requires careful, state-specific legal drafting and genuine loss of certain control over transferred assets, working directly with an estate planning attorney rather than attempting a do-it-yourself approach is a reasonable and often necessary step for this particular strategy.
5. Diversification and Asset Titling
How assets are titled, held individually, jointly with a spouse, or through a specific legal structure, meaningfully affects their exposure to creditor claims, and diversifying assets across different protected and unprotected categories rather than concentrating everything in a single vulnerable form provides genuine practical risk reduction. Certain states offer specific statutory protections for particular asset types, homestead exemptions for a primary residence in some states, for example, that vary considerably enough to be worth understanding specifically for your own state of residence.
Working with a financial advisor or estate planning attorney to review current asset titling against your specific risk exposure and state’s specific protections is a genuinely practical step that many people overlook until after a specific claim has already arisen.
What Should You Keep in Mind About Asset Protection Timing?
Asset protection planning is fundamentally about managing risk before a specific threat materializes, not about shielding assets from a lawsuit that has already been filed or a creditor claim that already exists, since most jurisdictions have specific fraudulent transfer or fraudulent conveyance laws designed to unwind transfers made with the specific intent to evade an existing, known obligation. Courts generally evaluate the timing and circumstances of asset transfers carefully, and a transfer made shortly before or after a specific claim arises faces considerably more legal scrutiny than the same transfer made years earlier as part of a broader, ordinary financial plan.
This is precisely why financial professionals consistently emphasize starting asset protection planning early, as a normal part of general financial and estate planning, rather than treating it as an emergency response to a specific, already-existing threat.
How Should You Choose Which Strategies Apply to You?
The right combination of these five strategies depends considerably on individual circumstances: business owners and licensed professionals generally need more thorough entity structuring and liability insurance than someone without significant business or professional liability exposure, while someone primarily concerned with long-term retirement security might prioritize maximizing protected retirement account contributions specifically. A qualified financial advisor’s guidance can help evaluate which specific combination of these approaches best fits a particular financial situation, income level, and risk exposure.
This article provides general educational information rather than personalized financial or legal advice, and anyone making specific asset protection decisions should consult a qualified financial advisor or attorney familiar with their particular state’s laws and personal circumstances before acting.
Conclusion
Genuine asset protection relies on five well-documented strategies, adequate insurance, proper business entity structuring, retirement account protections, carefully planned trusts, and thoughtful asset diversification and titling, each implemented proactively before a specific threat arises rather than reactively afterward. Since asset protection law varies considerably by state and individual circumstance, consulting a qualified financial advisor or attorney remains the most reliable way to build a plan genuinely suited to your own situation.
Frequently Asked Questions
Is asset protection planning only relevant for wealthy individuals?
No. While strategies vary by asset level, basic steps like adequate insurance coverage and proper business entity structuring are genuinely useful protective measures for a wide range of income and asset levels, not only high net worth individuals specifically.
Can I protect assets after a lawsuit has already been filed?
This is considerably more legally risky and often ineffective. Fraudulent transfer laws generally allow courts to unwind asset transfers made specifically to evade an existing, known claim, making early planning far more reliable and legally sound.
Do retirement accounts always receive full creditor protection?
Employer-sponsored plans generally receive strong federal protection under ERISA, but individual retirement account protection varies considerably by state, so checking your specific state’s rules is a genuinely important step for accurate planning.
Is forming an LLC enough to fully protect personal assets from business liability?
Not automatically. The entity must be properly maintained through genuine formalities, separate accounts, adequate capitalization, and accurate records, since courts can disregard the entity’s separation if it’s treated as a mere formality.
Should I consult a professional before implementing asset protection strategies?
Yes, generally. Asset protection law is genuinely complex and varies by state, so working with a qualified attorney or financial advisor helps ensure any specific strategy is implemented correctly and legally for your situation.

Haslhof Explained: The Real German and Austrian Villages Behind This Place Name

Gaymetu E: What This Gaming Community Site Publishes

Who Is Arabella Sezen Oz? The Fascinating Life Story of Dr. Mehmet Oz’s Daughter

Who Was Saul Consuelos? The Full Life Story of Mark Consuelos’ Father

Who Is Diane Addonizio? The Verified Facts About Howie Long’s Wife

What Does “Landslide” by Fleetwood Mac Actually Mean?

Who Is Jaisal Andrews? Inside the Life of Naveen Andrews’ Son

Who Is Kerri Browitt Caviezel? The Inspiring Life Story of Jim Caviezel’s Wife

Who Is Saffron Le Bon? The Untold Life Story of Benjamin Compston’s Wife

Who Is Sue Johnston? The Remarkable Life Story of Joel Palmentor’s Mother

Who Is Tanja Rosner? The Untold Life Story of Tate McRae’s Mother

Who Is Otelia Cox? The Remarkable Life Story of Tony Cox’s Wife
-
 Celebrity1 month ago
Who Is Jaisal Andrews? Inside the Life of Naveen Andrews’ Son
-
 Celebrity4 weeks ago
Who Is Kerri Browitt Caviezel? The Inspiring Life Story of Jim Caviezel’s Wife
-
 Celebrity4 weeks ago
Who Is Saffron Le Bon? The Untold Life Story of Benjamin Compston’s Wife
-
 Celebrity4 weeks ago
Who Is Sue Johnston? The Remarkable Life Story of Joel Palmentor’s Mother
-
 Celebrity4 weeks ago
Who Is Tanja Rosner? The Untold Life Story of Tate McRae’s Mother
-
 Celebrity3 weeks ago
Who Is Otelia Cox? The Remarkable Life Story of Tony Cox’s Wife
-
 Celebrity4 weeks ago
Who Is Amanda Redman? The Inspiring Life Story of Joan Redman’s Daughter
-
 Technology3 weeks ago
FintechZoom.io Explained: What to Verify Before Trusting This Site