Business
Understanding Two Common Funding Options for Small Businesses

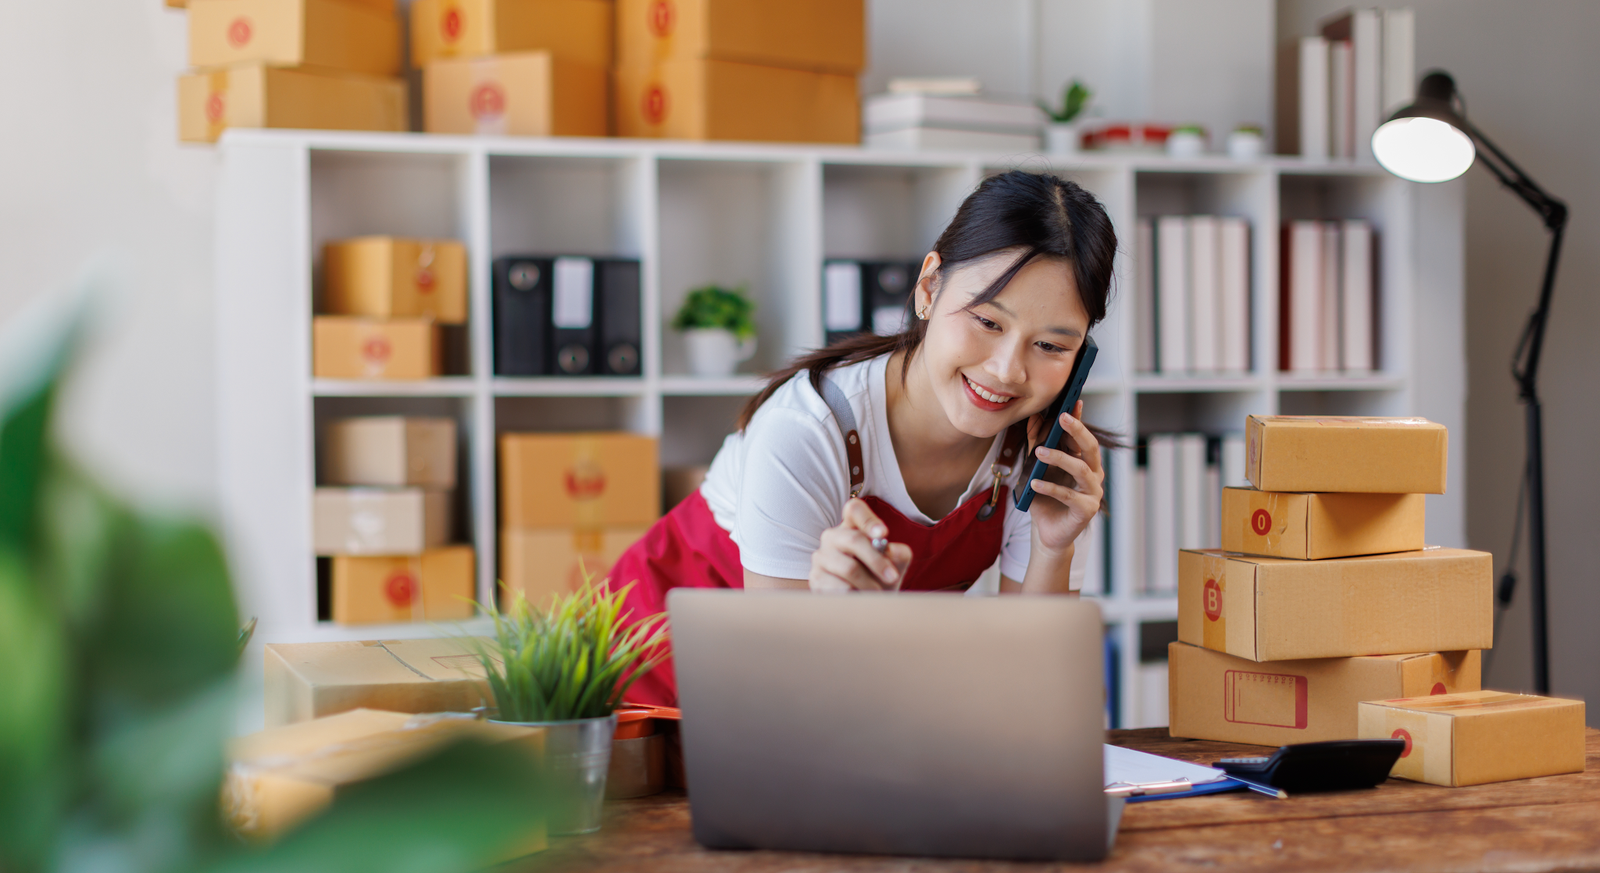
U.S.-based small businesses may require additional funds from outside sources to run their operations, pay bills, or expand their business. While seeking sources of funds, most business owners tend to evaluate the services provided by receivable financing companies against those offered by conventional lending institutions.
What Are Receivable Financing Companies?
Receivable financing companies offer you money based on your unpaid invoices. This means that instead of the normal waiting periods of 30, 60, or even 90 days after sending out invoices, a business can get part of the money right away. These kinds of companies can either raise a certain percentage of the invoice amount, or they can buy the receivables completely. A lot of receivable financing companies concentrate on how good your customers are at paying (e.g., their creditworthiness) rather than the credit profile of your business. That is why receivable financing is a workable solution for companies that have excellent clients but little or no credit history.
How Traditional Lenders Work
Traditional lenders are entities like banks and credit unions that offer loans to borrowers based on their creditworthiness, their financial history, and the value of their collateral. Unlike a company that offers receivable financing, traditional lenders typically have more stringent loan approval criteria and require more documentation to process your loan application. The lending process from a traditional lender can take several weeks or even longer. This makes them less than ideal for business owners who need access to quick funding. Although traditional lenders often provide lower-cost financing compared to alternative sources, they still have various requirements that may limit access to many of the smaller businesses in the marketplace.
Criteria for Approval: Revenue V/S Credit
Among the main contrasts between receivable financing companies and regular banks, the criteria used in approvals can be noted. Receivable financing firms consider how good the history of payments is for your accounts receivable. The better the payment records, the higher the chances you will have for approval. In essence, the emphasis will shift from your company’s credit rating. For their part, regular banks will value credit ratings more highly, alongside financials and collateral.
Funding Speed and Accessibility
Speed is another important point to consider. Funding companies that offer receivable financing have a reputation for rapid approvals and funding so fast that it can be done in just a couple of days. As they are based on the bills that have already been issued, these receivable financing companies can accelerate the process and deliver instant liquidity. This makes it a tool of great help to those businesses that struggle with cash flow. However, traditional banks have a much longer procedure for lending approval. Although they can offer good terms, the fact that the money can only be disbursed after a long time becomes a disadvantage if one needs money fast.
How The Two Repayment Structures Differ
Unlike an invoice, the payment structure of both options is completely different; with accounts receivable finance, payments are due only when your customers pay their invoices. The point at which your customers make payment on their outstanding invoices is what the finance company uses to determine whether or not they will collect their portion of the invoice, and they will have to do that with many customers. Payment is not made monthly on an established schedule like traditional lending institutions; instead, payment is based on your customers’ payment patterns and, as such, could lead some businesses with inconsistent revenues to have difficulty managing their business.
The Importance of Costs and Rates
Cost is a critical factor when deciding whether to go with accounts receivable financing companies or conventional lenders. While traditional loans have relatively low interest rates, funding companies have high fees that are dependent on the value of invoices. In this case, the charges incurred by receivable financing companies are commonly known as receivable factoring rates. The factors that influence these rates include risks associated with customers, the number of invoices, and the time required for payment.
When to Opt for Receivable Financing
Businesses that face working with payment terms but want to maintain cash flow on a regular basis fit perfectly with receivable financing companies. Manufacturers, distributors, and staffing firms are some of the sectors that generally resort to this method. For businesses with dependable clients who still suffer from cash flow constraints, receivable financing companies offer a way to have uninterrupted access to capital without having to acquire debt in a conventional manner.
Conclusion
When deciding between traditional lenders’ finance options through a receivable financing option, consider what is most important for your business. If cash flow requires quick access to cash with cash flows, and receivables are strong, then working with a receivable finance company may provide you with a very flexible option. If you qualify for a lower-cost financing source and can wait for approval, then you will likely want to work with a traditional lending institution. There are differences in the speed of approval, processing time for receiving funds, and the repayment terms of the funding sources to determine which funding source will be the best fit for the growth of your business.


Understanding Two Common Funding Options for Small Businesses

Who Is Kerrie McCarver? The Remarkable Life of the Woman Who Spent 21 Years With the “Killer”

Wearing a Short Set Without Looking Like Pyjamas

Who Is Carrie Schenken? The Inspiring Life Story of Amanda Bearse’s Wife

Who Is Maxine Sneed? The Remarkable Life of Tommy Chong’s Ex-Wife

Croydon Extensions: Why This Is One of London’s Easier Boroughs to Extend In

What Is OpenSkyNews and Who Are Its Two Co-Founders?

Who Is Tanja Rosner? The Untold Life Story of Tate McRae’s Mother

Who Is Jaisal Andrews? Inside the Life of Naveen Andrews’ Son

Who Is Saffron Le Bon? The Untold Life Story of Benjamin Compston’s Wife

Who Is Kerri Browitt Caviezel? The Inspiring Life Story of Jim Caviezel’s Wife

Who Is Otelia Cox? The Remarkable Life Story of Tony Cox’s Wife
-
 Entertainment3 months ago
What Is OpenSkyNews and Who Are Its Two Co-Founders?
-
 Celebrity3 months ago
Who Is Tanja Rosner? The Untold Life Story of Tate McRae’s Mother
-
 Celebrity3 months ago
Who Is Jaisal Andrews? Inside the Life of Naveen Andrews’ Son
-
 Celebrity3 months ago
Who Is Saffron Le Bon? The Untold Life Story of Benjamin Compston’s Wife
-
 Celebrity3 months ago
Who Is Kerri Browitt Caviezel? The Inspiring Life Story of Jim Caviezel’s Wife
-
 Celebrity3 months ago
Who Is Otelia Cox? The Remarkable Life Story of Tony Cox’s Wife
-
 Celebrity3 months ago
Who Is Sue Johnston? The Remarkable Life Story of Joel Palmentor’s Mother
-
 Software2 months ago
Voozon.com Explained: What It Really Is Behind the “Knowledge Platform” Label